A dramatized courtroom story exploring a real and growing legal issue: local governments seizing and auctioning homes over small unpaid debts.
The Story
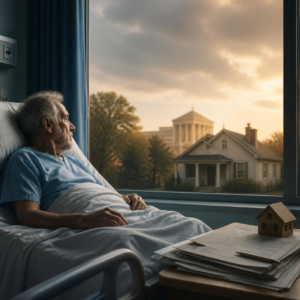
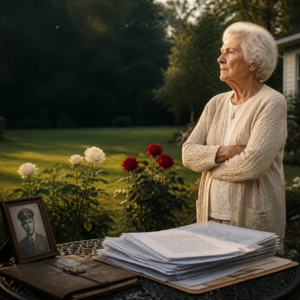
He raised his children in that house. Fifty years of birthdays, holidays, and ordinary Tuesdays happened inside those walls. At 79, he was still living there when a routine code violation an unpaid $40 fee set off a chain of events that would nearly cost him everything.
While he was hospitalized for four months recovering from triple bypass surgery, the fee sat unpaid. Penalties accumulated. Notices were mailed to an empty house. By the time he was discharged and strong enough to check his mail, the city had already auctioned his home to recover the debt.
The sale price: $11,000. The home’s actual value: roughly $400,000.
Inside the Courtroom
The city’s position rested on procedure: notices were mailed to the property address as required, the debt went unpaid for six months, and the auction followed municipal code to the letter. From a purely procedural standpoint, the city argued, everything was done correctly.
His account exposed the human cost that procedure alone doesn’t capture. He wasn’t ignoring the notices he was recovering from major heart surgery, unable to access mail sent to a house he couldn’t safely return to. A $40 debt, through penalties and auction fees, cost him a home worth roughly forty times the sale price it fetched.
The court’s ruling addressed both the process and the outcome and found the gap between them impossible to ignore.
What The Law Actually Says
This story is fictional, but the underlying legal issue sometimes called “home equity theft” is very real, and it has recently drawn attention from the U.S. Supreme Court.
In the 2023 case Tyler v. Hennepin County, the U.S. Supreme Court ruled unanimously that when a government seizes and sells a property to satisfy a tax or fee debt, and keeps sale proceeds far exceeding the actual debt owed, it violates the Takings Clause of the Fifth Amendment. In that case, a $15,000 tax debt resulted in the county keeping the full proceeds of a $40,000 home sale the Court found the homeowner was entitled to the surplus equity.
Following that ruling, many states have reformed or are actively reforming their tax and code-violation foreclosure laws to require:
- Adequate notice reasonably calculated to reach the actual homeowner, not just mailed to an address that may be inaccessible
- Proportionality between the debt owed and the value seized
- Return of surplus equity meaning a homeowner is generally entitled to receive the difference between what they owed and what the property actually sold for
- Additional protections for vulnerable homeowners, including hospitalized, elderly, or disabled residents who can demonstrate they were unable to respond to notices
Some states still have gaps in these protections, which is why this issue continues to generate litigation and legislative reform efforts nationwide.
What To Do If You Or A Family Member Faces This Situation
- Respond to any code violation or tax notice immediately, even a small one penalties and fees can escalate faster than people expect.
- If a family member is hospitalized or incapacitated, designate someone to check their mail and manage urgent bills during that time, or set up mail forwarding in advance if possible.
- If a property has already been sold at auction, consult an attorney immediately under Tyler v. Hennepin County and resulting state reforms, you may be entitled to surplus equity or even a reversal of the sale in cases involving inadequate notice.
- Contact your state’s consumer protection office or a legal aid organization that specializes in foreclosure and tax sale defense many offer free consultations for cases involving elderly or hospitalized homeowners.
- Know your state’s specific notice and equity protection laws, since they vary significantly and have been changing rapidly since 2023.
Final Thoughts
Whether or not this exact story happened, the legal principle behind it reflects a real and recent shift in American law: governments generally cannot use a small debt as justification to seize and profit from a homeowner’s full equity, particularly when notice was inadequate or the homeowner was unable to respond through no fault of their own.
Have you or a family member ever dealt with a property tax or code violation issue that escalated further than it should have? Share your experience in the comments below.